You've probably already felt the frustration. You found a parcel you like, ran the numbers in your head, and then a bank asked for more paperwork, more time, and more cash upfront than the land itself seemed to justify. For many buyers, that's the moment the dream of owning a piece of ground starts feeling distant, even when the land looks affordable on paper. Owner financed land changes that conversation because the seller, not a bank, can provide the purchase money and set the terms directly. That doesn't make it casual or risk-free, but it does make land ownership possible for buyers who need a different path. Table of Contents Why Traditional Land Loans Feel Impossible How Owner Financing Works The basic moving parts Why the title question matters Owner Financing vs Bank Loans The Real Risks and How to Protect Yourself The title and lien problem What to verify before you sign How LandZero FlexPay Makes It Simple How the process is organized Why this model matters Can You Build on Owner Financed Land The hidden constraints buyers miss Due diligence that keeps the deal usable Is Owner Financing Right for Your Situation When it points you toward a bank instead A simple decision filter Why Traditional Land Loans Feel Impossible A buyer can have decent income, steady work, and a clear plan for the parcel, then still hear no from a lender because vacant land is treated as higher risk than improved property. That's especially discouraging when the buyer is looking at a simple rural lot, not a complicated commercial project. The land may be affordable, but the loan process can make it feel out of reach. The usual sticking points are familiar. Lenders often want more cash down, tighter credit, and cleaner documentation because raw land has fewer built-in protections than a house already connected to utilities. The result is a gap between what a buyer can responsibly afford and what the bank is willing to finance. That gap is exactly why owner financed land keeps showing up in the marketplace. It gives the seller room to negotiate directly with the buyer instead of forcing the deal through a bank's underwriting template. For buyers with thin credit, limited savings, or a timeline that doesn't fit a slow approval process, that flexibility can be the difference between buying and waiting indefinitely. This guide on buying land with no credit is a useful companion if your main obstacle is lender approval rather than the land itself. Practical rule: if the lender is judging the parcel more harshly than the buyer's actual plan for it, owner financing can become the more realistic path. That's why many first-time buyers start looking beyond traditional land loans. They're not trying to avoid responsibility. They're trying to find a structure that matches how land is bought, held, and improved in the world. How Owner Financing Works At its simplest, owner financing means the seller acts like the lender. Instead of borrowing from a bank, the buyer agrees to repay the seller over time under terms both sides negotiate. Those terms usually cover the down payment, the interest rate, the monthly installment, the length of the deal, and what happens at the end if there's a balloon payment. The basic moving parts A seller-financed land deal usually starts with a few negotiated terms that shape the whole arrangement. The down payment shows how much the buyer brings up front, the interest rate sets the cost of carrying the balance, and the payment schedule determines how quickly the principal is reduced. In many land transactions, the structure also includes a balloon payment, which means a larger balance comes due at the end of the term. The paperwork typically starts with a promissory note, which spells out the payment obligation. Then the deal is secured by either a deed of trust or mortgage, or by a land contract. Under a deed of trust or mortgage structure, the buyer can receive title with the seller keeping a lien position. Under a land contract, the seller commonly keeps legal title until the buyer pays in full (The Land Geek). That title detail is the part many buyers miss. In some deals, the buyer is using the land and making payments, but does not fully hold title yet. In others, title transfers at closing and the seller keeps a security interest. The legal structure changes who bears what risk, so the document type matters just as much as the monthly payment. Practical rule: don't ask only, “Can I afford the payment?” Ask, “What exactly do I own during the payment period?” Why the title question matters A land contract can be useful, but it can also leave a buyer with less control than expected if the seller keeps title until payoff. A deed of trust or mortgage structure can offer stronger title mechanics for the buyer while still protecting the seller's interest. That is why the ownership question deserves a direct answer before signing anything. The easiest way to think about it is this. Owner financing is not just a payment plan. It is a legal structure that decides whether you are building equity under your name now, or waiting for full title until the obligation is finished. Owner Financing vs Bank Loans A buyer can close on the same parcel in two very different ways, and the ownership mechanics change just as much as the payment terms. A bank loan follows lender rules and a formal underwriting process. Owner financing lets the seller set the terms directly, which can make the deal possible when a bank says no. Factor Bank Loan Owner Financing Down payment Often set by lender rules and tied to qualification standards Negotiated between buyer and seller Credit requirements Usually strict Often more flexible Approval speed Slower, with more documentation Faster, because the parties negotiate directly Interest rate Usually lower Often higher Flexibility Limited by underwriting templates Highly customizable Total cost Can be lower if
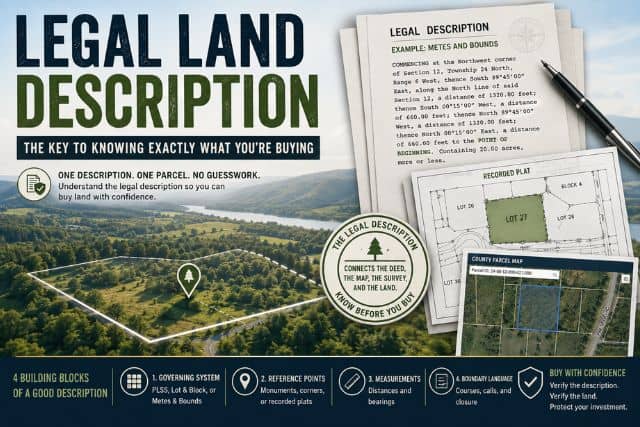
You can be staring at a cheap land listing right now, with a pretty aerial photo, a county map, and maybe a street address that sounds close enough to what you want. Then you click around and realize the listing doesn't clearly show the parcel identifier, the recorded plat, or the exact legal wording that tells you what land is for sale. That gap is where a lot of first-time buyers get stuck, because the legal land description is the document that ties together the deed, title, survey, county records, and the boundaries on the ground. If you're comparing rural lots, off-grid acreage, or a subdivision parcel, the description is not paperwork trivia. It's the controlling identifier that lets a title company, county recorder, and surveyor talk about the same piece of land without guessing. An address can change, a GPS pin can be off, but the legal description is what carries the parcel through ownership history and conveyance. Table of Contents Why the Legal Description Matters Before You Click Buy Why title, survey, and county records all care about the same wording The Four Building Blocks of a Legally Sufficient Description The four reference pieces that keep a parcel unambiguous Reading PLSS Descriptions Section by Section How the grid narrows the parcel Decoding Metes and Bounds Calls What the boundary language is doing How Lot and Block Descriptions Anchor to a Recorded Plat Why the plat is the real source document Matching the Right System to Your State and Parcel Don't trust geography alone Reading for Risk Hidden Inside the Description The hidden problems buyers miss Finding the Legal Description Before You Buy A simple retrieval workflow Pre-Purchase Verification Checklist Six checks that catch the most expensive mistakes What to do when something doesn't line up Glossary of Description Terms You Will See in Deeds Quick Reference Card You Can Keep by the Listing Why the Legal Description Matters Before You Click Buy A first-time buyer often starts with the easiest thing to understand, the listing photo. The next stop is usually the address, then the county map, then a parcel search that still feels vague because the map doesn't tell the whole story. That's where the legal description becomes the difference between buying land and buying uncertainty. The Bureau of Land Management defines a legal description as a written land description based on an approved and filed Federal land survey under the PLSS, or, where authorized, a protraction diagram, and otherwise by metes and bounds tied to monuments or other boundary references BLM land description specifications. In plain terms, it's the language that makes one parcel legally distinct from every other parcel around it. An address points mail to a place, but the legal description points ownership to the exact tract. Why title, survey, and county records all care about the same wording County recorders index deeds by the description, title companies rely on it to insure the right parcel, and surveyors use it to locate the land on the ground. That's why a description isn't just a label, it's the written bridge between paper title and physical boundaries. If the wording is incomplete or unclear, the problem doesn't stay on the page, it can affect what you own. Practical rule: if you can't trace the legal description to a recorded instrument or survey, you don't yet know exactly what's being offered. This matters most for remote buyers, out-of-state buyers, and anyone comparing vacant land listings online. A map pin can be close and still not prove the parcel line, the easement, or the exclusion language. Before money changes hands, the legal description needs to match the land you think you're buying, not just the land the listing photo suggests. The Four Building Blocks of a Legally Sufficient Description A legally sufficient description has one job, identify the parcel to the exclusion of all other land or give a reliable way to locate it from other sources BLM land description specifications. For a buyer, that means the wording has to do more than sound official. It has to point to one specific tract, and it has to do so in a way a recorder, surveyor, or title company can follow without guessing. Survey guidance also treats good parcel descriptions as something that should be plottable, locatable on the ground, and, when applicable, mathematically close minimum standards for parcel legal descriptions. If one of those pieces is missing, the description gets harder to trust. The four reference pieces that keep a parcel unambiguous For PLSS-based parcels, Colorado land-record guidance points to the core reference data that make a description readable, including the principal meridian, township and range, section number, quarter section or quarter-quarter section, acreage, and a reception number or deed date/book-and-page reference. Those elements work like a survey address. Each one narrows the tract until the parcel can be tied back to the public record and the ground itself Colorado land-record guidance. A useful way to read those pieces is in order: Principal meridian: the north-south reference line that starts the grid. Township and range: the grid location relative to that reference. Section or lot identifier: the specific one-square-mile unit or recorded lot. Acreage or recording reference: the size or the document trail that ties the parcel to the record. Metes and bounds descriptions rely on a different set of clues, but the logic is the same. The description needs a point of beginning, boundary calls, monuments or landmarks, and a closing call back to the start minimum standards for parcel legal descriptions. If those pieces are missing, the deed may still look formal, yet it may leave too much room for doubt about where the line runs. That is where buyers need to slow down. A clean description does not have to be long, but it does have to be complete enough that another professional can put the same tract on the ground and get the same result. When a description leaves out the tie to
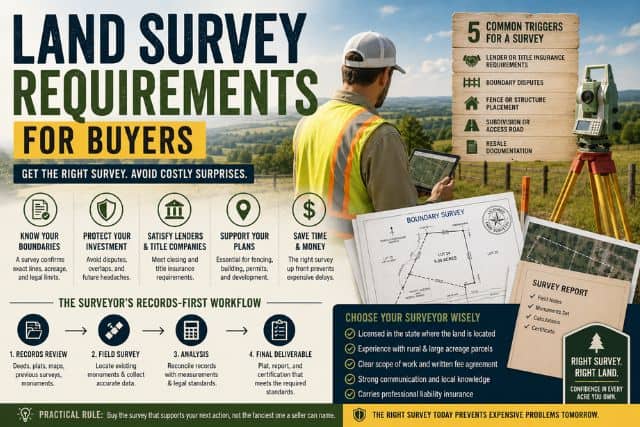
Land survey requirements are not a single federal rule, and a survey for closing can differ sharply from one for title insurance, a fence, or a build permit. The standard you need depends on the use case, and the deliverable changes with it, so a cheap survey can still be the wrong survey if it doesn't match the job. You're usually learning this the hard way, halfway through a purchase, with a seller, lender, title company, or county office asking for something you didn't expect. That's where first-time buyers get burned. They either order too little, too late, or they pay for a fancy plan when all they needed was a clean boundary document that fits the transaction. Table of Contents What Land Survey Requirements Actually Mean for a Buyer What the phrase really covers When You Actually Need a Survey and When You Don't Five common triggers The Records-First Workflow a Licensed Surveyor Runs What gets reviewed first How State-Specific Standards Change the Deliverable Why this changes your paperwork Choosing the Right Licensed Surveyor for Your Parcel What to verify before you sign A Realistic Timeline and the Documents You Should Expect What the timeline often looks like Final Checklist Before and After the Surveyor Leaves Red flags that mean you should order a new survey What Land Survey Requirements Actually Mean for a Buyer You're in escrow on a five-acre parcel in a state you've never lived in, and someone suddenly says you “need a survey.” That phrase sounds simple, but it's really shorthand for a decision about what problem the survey has to solve. A survey for closing doesn't have the same purpose as a survey for a fence line, a building permit, or title insurance. The oldest mistake buyers make is treating land survey requirements like a universal checklist. They're not. The land is described through legal records, and in much of the country that framework traces back to the Public Land Survey System, created by the Land Ordinance of 1785 after the 1783 Treaty of Paris to divide and sell public land (PLSS background). That history still matters because the boundary you think you bought is the boundary the record can prove. What the phrase really covers For a buyer, "requirements" usually means three things at once: the legal purpose, the technical standard, and the deliverable. The legal purpose might be closing, title insurance, or building readiness. The technical standard tells the surveyor what framework to use. The deliverable is the thing you receive, such as a plat, monument set, or digital file. Remote investors, off-grid buyers, and first-time buyers using owner financing feel this most. They often buy land without standing on it first, so the survey becomes the only hard evidence of what the parcel can support. If you're also sorting out zoning and land use, property zoning in the United States shapes what a survey needs to prove before you spend money on improvements. Practical rule: buy the survey that supports your next action, not the fanciest one a seller can name. The point is simple. If you know whether the parcel is headed toward closing, fencing, building, or title work, you can ask for the right survey the first time. When You Actually Need a Survey and When You Don't A survey is not mandatory just because you're buying land. It becomes necessary when a lender, title underwriter, county office, or your own plans need the boundary documented in a particular way. Miss that distinction and you'll either overspend or get stuck with a parcel you can't use the way you intended. Five common triggers Lender or title insurance demand: The surveyor is being asked to confirm the boundary and show what could affect insurability or financing. If the deal needs that paper trail, you need a survey that satisfies the underwriter, not just your curiosity. Boundary dispute: Now the survey has to reconcile record evidence and physical evidence, because the issue is no longer academic. The buyer pays to find out where the legal line sits. Fence or structure placement: The surveyor is helping you avoid crossing the line before you pour concrete or set posts. That's a different job from a closing survey because the layout has to support construction decisions. Subdivision or access road: Here the survey supports a change in how the parcel is legally described or accessed. That often means more documentation and stricter technical control. Resale documentation: A clean survey can make future marketing easier, but only if it matches the parcel's current condition. Reusing an old one is risky if anything changed on the ground. A buyer who only needs to close on raw land may get a boundary plat and legal description. A buyer adding a fence usually needs corner confidence and monument ties. A buyer preparing a building site may need boundary work plus additional site data tied to the proposed improvement. Different purpose, different product. If the survey is mainly about parcel division or access planning, these subdivision steps show why the deliverable quickly becomes more than a simple sketch. If the next step is legal transfer, get enough survey to clear title. If the next step is building, get enough survey to place improvements safely. If the next step is just watching the market, skip the expense for now. That rule will save you money more often than any checklist. The Records-First Workflow a Licensed Surveyor Runs A competent boundary survey starts in the office, not in the field. The surveyor reads the deed, studies the parcel's recorded description, and pulls enough adjoining evidence to understand what the record claims before anyone drives a stake. That is the difference between a defensible survey and a map that looks neat but can't survive a dispute. What gets reviewed first The surveyor should gather the recorded description, adjoining deeds, plats, right-of-way records, easements, and any prior surveys that touch the parcel. Then comes the field search for monuments and other controlling
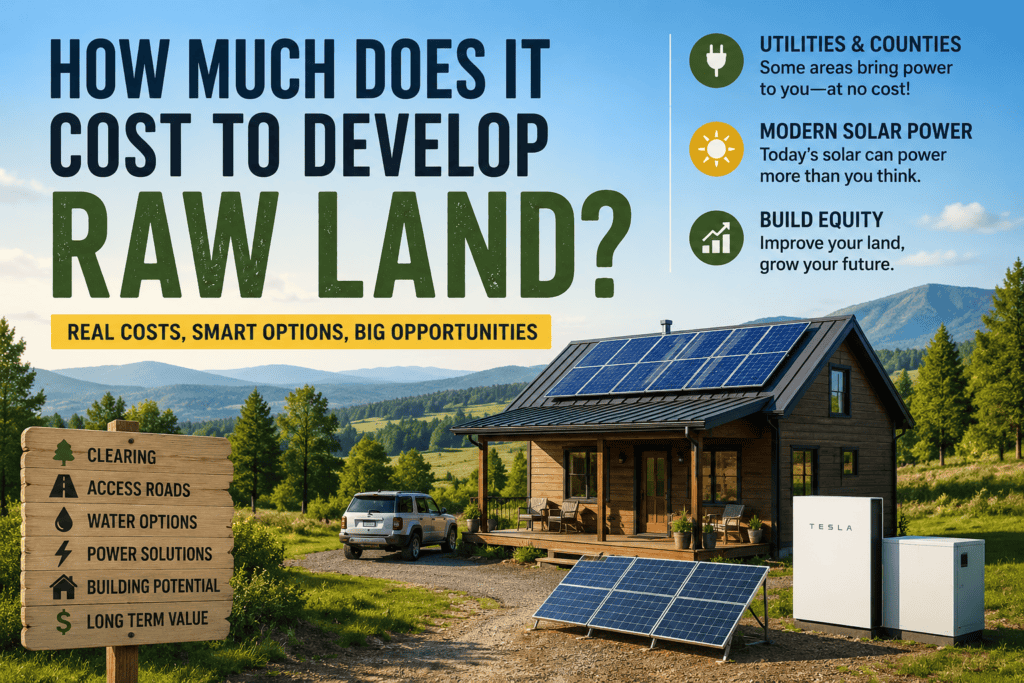
One of the biggest misconceptions about raw land is that development always costs a fortune. In reality, many landowners improve their property gradually over time, and modern technology has made rural living far easier and more affordable than it used to be. Some properties are already close to utilities, some counties actively encourage development, and many buyers today are choosing solar and off grid systems instead of relying entirely on traditional utility companies. For many people, developing land is less about “massive construction” and more about creating freedom, flexibility, and long term value. Developing Land Doesn’t Always Mean Building a House Immediately A lot of buyers purchase raw land with a long term plan. Some start with: You do not need to fully develop land all at once. Many landowners slowly improve their property over the years as their budget and plans evolve. Typical Land Improvement Costs Depending on the property, improvements may include: Improvement Typical Cost Range Land Survey $500 to $3,000 Driveway or Access Road $3,000 to $15,000 Septic System $5,000 to $20,000 Water Well $4,000 to $15,000 Basic Clearing $1,500 to $10,000 Power Connection Sometimes free to $30,000+ The important thing is that not every property needs every improvement. Some buyers intentionally seek: Which can dramatically reduce development costs. Some Counties and HOAs Help Bring Utilities In One thing many first time land buyers do not realize is that some counties, utility providers, and even HOAs actively encourage development. In growing rural areas, bringing power into a neighborhood benefits: Because of that, utility companies will sometimes extend power lines at little or no upfront cost to the property owner, especially if: This varies heavily by county and utility provider, but it is far more common than many buyers realize. Always ask: Sometimes the “future value” of the area is part of the equation. Off Grid Living Is Easier Than Ever Power today is not what it was 20 years ago. Modern solar technology has changed rural land development dramatically. Many landowners now choose: In some cases, solar can actually be cheaper than extending utility lines long distances. What Modern Solar Can Actually Power Today’s high end solar systems are capable of running far more than people expect. With properly designed systems and battery storage, many properties can power: The biggest factor is usually energy usage habits and battery capacity. Common Solar Setup Types Small Recreational Solar Setup Great for: Usually powers: Often portable and inexpensive. Mid Size Hybrid Solar System Common for: Can power: Often paired with generator backup. Full Home Solar + Battery Systems Modern systems from companies like Tesla and other solar manufacturers can support full time living when properly sized. Examples include: Tesla’s Powerwall systems, for example, are designed to store energy for nighttime use, outages, and off grid applications. Many modern off grid homes today operate very similarly to traditional homes. Land Development Is Often About Flexibility One reason people love raw land is flexibility. Unlike buying an expensive finished property, land owners can: Some buyers spend very little initially and simply enjoy the property recreationally while planning future improvements. The Biggest Money Saving Tip The best land deals are often properties that already have: Even small existing improvements can save thousands later. Final Thoughts Raw land development does not always need to be overwhelming or extremely expensive. Modern solar technology, expanding rural infrastructure, and flexible development options have made land ownership far more accessible than many people realize. Some buyers fully develop property immediately. Others improve land gradually over time while enjoying the freedom and long term value that land ownership can provide. The key is finding property that matches your goals, budget, and vision for the future.
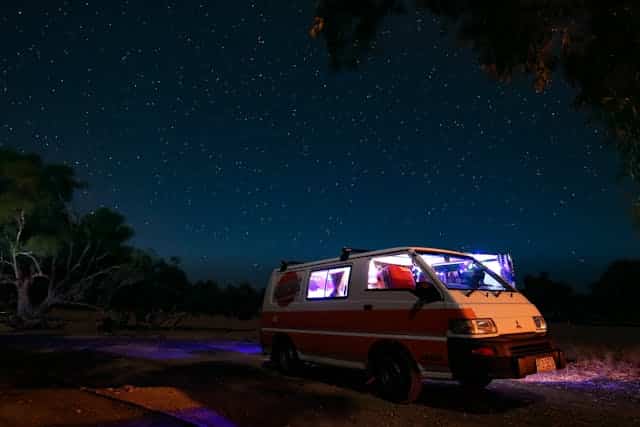
In 2018, I bought a remote 1.25 acre piece of land in Cochise County, Arizona for just around $3,000. At the time this was a going rate for most of the land there. People thought I was crazy, there was nothing on it. No power. No water. Just dirt, desert shrubs, and a lot of sun. Some friends and family said it was worthless land, but after you read this you’ll see that they were far from correct about that. My vision was clear, a campsite my friends and I could use without the hassle of park passes or high camping fees. And so, here’s my story on how I made that happen. I didn’t buy land to build a house. I bought it as a project for improvement, a campsite I could use and potential flip down the line. I figured, well, people buy junk homes and fix them. But what if I bought just blank land and turned it into an awesome campsite. I know I wanted a place I could retreat to on weekends, a set up no stress camping spot where I could take friends, make a fire, and enjoy the stars without hearing a single car. I gave myself a challenge: Make my land a super nice camping spot for under $1,000. Here’s how I pulled it off. The Budget Build Begins The parcel is in Cochise County, Arizona, which at the time was super cheap land. Most lots I looked at were in the $3k range so this wasn’t some rare lot, it was just how the area was at the time. It had no utilities, no neighbors but it was level and it did have a dirt road to it. The area allowed recreational camping, and as long as I’m not permanently living on it, I didn’t need permits for temporary improvements. Which made my low cost project possible. On a side note from our company, we still have some great lots in arizona, and it’s land under $5k <——— Click Here At first glance, it was just scrub brush and packed dirt, I did have a survey done to make sure all this was going to be done on my land and not the neighbors. But I could see the layout I wanted, a nice flat area I could camp on, trail to a small shed I could put out and there, campfire spot and positioned on the elevated land so we had a view of the mountains in the background. Overall, the vision was there that I had. And I had seen really cool camping spot ideas on the Hipcamp app for ideas. Step 1: Clearing the camping spot ($75) I didn’t rent any machines, it was mainly desert brush so I went full DIY with help from a good friend. I brought a machete, some garden tools, a thick metal rake and brought an old chainsaw just incase to dig down in the dirt. We cleared a 20×20-foot section of land, removing all shrubs, plants, rocks and raked it smooth. It took a weekend, some sore arms, and a lot of sunscreen. Tip: We learned quite quickly you should first mark out the square area with stakes and rope, otherwise you tend to go off the planned area. Step 2: Gravel for the Car Pad ($150) The dirt was fine in dry weather, but I wanted a stable place to park the car should heavy rains come. I had two yards of gravel delivered by a local guy who does side jobs in the area. I spread it by hand and edged it with scrap wood to make a nice parking area. It didn’t have much look to it and I was worried the wood alone wouldn’t hold it together, so we also stacked rocks we collected from the clearing to go around the scrap wood and gravel, which gave it a more car parking look and kept the wood in a stable spot. It works perfectly and looks great. Step 3: Fire Pit + Outdoor Cooking Setup ($40) The fire pit we wanted just outside the cleared zone and in the best spot for a view of the mountains. We made stepping stones and cleared a small trail to it and then cleared the pit area. I gathered large flat rocks from around the property and bought some bricks. I don’t know the cost of new bricks but we bought them from a guy that basically just wanted them removed for taking up space. I leveled the surrounding dirt, we dug out a good sized fire pit hole and lined the bricks to make a wall down in the pit. We packed it with watered down dirt and around the rim laid down the flat stones around it. We also found an old top to what must have been a huge grill on the offer up app, we lay this over the stones when we bbq and it works like a charm. One of the best Tri-Tip steaks we have had. Tip: Keep in Mind, a lot of the shrubs or desert plants we took out we later replanted in a thoughtfully designed way. Having a stylish garden look is usually costly, but we thought, why not use the free plants we have already. In this case we did a bit of a circular plant design that would go around the fire pit chairs, leaving the dirt area for the chairs around the pit and the plants surrounding the chairs. Step 4: Shade and Seating ($50) Arizona sun isn’t a joke. I picked up a huge tarp cover off Facebook Marketplace and strung it down so we could sit and relax in the cleared area over extending to cover the car as well. We put in the basic hook ups like dug holes with PVC pipes for the poles and metal rods for the ropes to hold it down. Stuff like seats, table set up and beer cooler
In today’s world of tight lending standards and rising interest rates, securing a traditional land loan can be nearly impossible for many buyers. Banks and large financial institutions typically require high credit scores, extensive paperwork, and often a sizable down payment. Even many owner-financed land deals include a credit check and place a lien on your credit report to ensure timely payments. For those with low or no credit, these barriers can make land ownership feel out of reach. That’s where the opportunity of buying land no credit comes in as a powerful shortcut in the world of real estate. ✅ Key Takeaways: Buying land with no credit is more accessible than ever, with online platforms and owner-financed options removing the need for traditional credit checks. TL;DR: This guide shows how to buy land with no credit using seller-financed options. It’s a shortcut to land ownership, no bank needed, no credit score required. Why Buying Land with No Credit Is a Smart Move The concept of buying land no credit provides a game changing solution for those to enter the real estate game. As they are considered underserved by traditional financial systems. With no need for a high credit score, the door opens to people who are self employed, have gone through bankruptcy, too many missed payments, or simply don’t use credit regularly enough to build it. Many conventional paths to land ownership come with red tape, delays, and endless rejection. But by sidestepping banks and credit checks, you can access property faster, easier, and with greater peace of mind. It’s an ideal option for individuals who are financially responsible but may not fit the narrow definition of a “prime borrower.” If you’re unfamiliar with how credit works or how it can impact your future goals, take a look at the official US consumer finance article here: What is a Credit Score A Real Estate Shortcut: Buying Land Online A true real estate shortcut is taking advantage of platforms that let you buy land online without the credit obstacles. At LandZero, for example, we own 100% of the land we sell. This means we act as our own bank, offering flexible monthly payment plans without the need to pull your credit or place a lien on it. If you have poor credit, or no credit at all, you will still be approved. This model offers more than just convenience; it provides access to a real, tangible asset. Buying land no credit is one of the few ways to own appreciating property with little upfront risk. It’s a rare gateway to long term financial security. The Benefits of Owning Land When you choose the buying land no credit method, you’re not just avoiding banks, you’re investing in something solid. Land ownership as an entry into asset diversification offers numerous advantages: These benefits make land one of the most stable and rewarding investments available, especially for those looking for ways to secure their future without relying on traditional finance, or complete rejection into real estate ownership. Understanding How No Credit Land Deals Work & Common Misconceptions Many people assume that buying land no credit must be risky or too good to be true. In reality, the process is straightforward and secure when working with reputable sellers. These deals often involve seller financing, where the landowner holds the loan instead of a bank. A land purchase agreement is signed outlining the payment plan, and ownership is transferred once the land is paid off. There is no need for a credit check, and buyers aren’t penalized for their financial past. It’s a legitimate path to ownership, not a loophole or scam. The expected requirement is that you make your payments as the company who owns the land has not choice but to default and take the land back should you not pay on it. Comparing Buying Land No Credit vs. Traditional Financing When comparing buying land no credit to traditional bank financing, the differences are clear: For buyers who are eager to secure land without financial red tape, the no credit route is often the better, faster, and less stressful option. If you’ve struggled with loan denials or poor credit scores, don’t give up on your dreams of land ownership. Buying land with no credit is not just possible; it’s practical, attainable, and increasingly popular. Platforms like LandZero are making this a reality for everyday buyers across the country. The path to ownership no longer requires jumping through hoops. With the right strategy, you can skip the credit check, start small with cheap land for sale, and grow your investment with confidence. It’s time to stop letting your credit score hold you back if you want to start building your future with real estate. Explore our listings and see how easy it is to start buying land no credit today: See Land for sale in America We have a new page as well for foreigners with questions on buying land in America that has been generated in the AI space, check it out. How to Buy Cheap Land in America
Escape rising costs and live on your own terms with affordable off-grid land. This guide reveals the top 10 U.S. locations where you can buy land for under $10K and build a self-sufficient future.
Buying Land in Colorado offers a lot of opportunity if you know what to look out for. This guide shares eight important tips to help you make a smart, informed decision when buying land in the state.
Finding the cheapest land in a state is a strategy many land investors use to capitalize on undervalued land to flip or hold a couple years for a nice return. While some land is at full value, there’s always some place in a state that hasn’t reached its full potential. Land in these spots is usually fire sold or easy to offer below value bids with motivated sellers. What the sellers don’t realize is that the land they are holding happens to be the lowest in the state, which often draws many buyers eventually and once these investros flip for higher the area in full sees values rise. Finding the cheapest land in a state is an online process you will learn today, but there’s also an important strategy to make sure the land isn’t cheap for a reason. You want to find the ones with potential and value return, which we will go over here. With the right tools and a sharp eye, you can uncover incredible land deals while avoiding money pits. This guide shows you exactly how. How To Find the Cheapest Land in Your State Using Online tools Step 1: Use Zillow’s Map Tool to Draw Target Zones Start by visiting Zillow and use the selector to only focus on land, removing all home options. Now, you want to start a narrow down process by selecting your target state. Use the “Draw” tool to circle the whole state you are interested in. Then: This helps you identify where the cheapest land clusters. Step 2: Refine the Circle Tool to Zoom In on Cheapest Clusters After spotting the general area with the cheapest listings, use the draw tool again, this time focusing on a tighter radius around those listings. They are always grouped together as the area is low cost all together in an area vs. other areas. This step reveals the true low-cost pockets within the state. Step 3: Analyze Listings for Hidden Red Flags Cheap land isn’t always good land. Common red flags include: You can do this quite easily by reading the listings, if it has an HOA then avoid it. The value usually won’t change with land like this as long term people don’t want to pay HOA dues, so the land will remain cheap. You can also use county GIS maps or contact the assessor to confirm access and zoning. Some land you cannot access, there’s simply no road to the area and with zoning, sometimes building is blocked by the county for various reasons. Some also have environmental issues, completely flooded wetlands land will never grow in value as you can’t do anything with it. So, if this is your results it’s time to start back over at step 1, now you’re looking for the second cheapest land in the state. You want to do this process till you find good standing land, buildable, accessible and without HOA dues. Step 4: Research the Area for Long-Term Potential Once you found the cheapest land with the qualifications mentioned in step 3 it’s time to research its potential. Cheap doesn’t mean worthless, it’s simply a price point, but for the greatest potential land add these qualifications to your search for the best chance of increased value over time. Free tools like Google Earth, Redfin, and public tax databases help validate your area. If you start to see that the area is developing a bit, the land is still low cost but growing slightly in value then it’s usually a good start. You can look under sold instead of for sale to see past values. At LandZero we have used this strategy for ages. Our customers throughout the years have seen major increase in value due to our ways to research land. We know the potential of the area, we know the prices and see value in that area over time. If you want some good examples visit our Land in America For Sale Step 5: Establish the Average Price Per Acre Use listings in your narrowed zone to calculate: This will give you a price benchmark and identify what’s actually a good deal versus just the cheapest land. If the acreage is super small then it’s cheap because of that, some large acre lots might be way cheaper by average cost per acre. People like large parcels of land, you have a better chance of gain with a 1 acre lot vs a 6000 sqft lot. Step 6: Set Alerts for Fire Sales and New Listings Use platforms like: Create alerts with your filters so you’re notified the moment a new listing hits your price range. Fire sales, estate sales, or out of state owners often price land to move fast. Being on top of new listings first might give you the jump on a fire sale in the area with the cheapest land for the ultimate immediate value upon ownership. Step 7: Make Aggressive Offers to Undercut the Market Once you know the average value, target listings that: Offer below the average and do it in bulk, many sellers take lower offers if they just want it gone. This won’t usually work for homes but for land it does, some just want it off their list so they don’t have to pay annual taxes anymore. If you have notifications on just send a 50% offer each time till someone bites. With these steps, you can start owning land for the best price possible in an area with great potential. In some cases you can make 300% or more just holding a couple years. These areas are often targeted eventually, people like cheap land prices and once the area is focused on by land buyers the value quickly goes up.
5 Key Signs You Should Sell or Hold Your Land Now If you’ve owned a parcel of land for a while, you’ve likely received unsolicited offers to buy it, especially during these times of inflation or economic uncertainty where land values are good and buying is hot. People started to see land as an asset to hold, especially those abroad. It gives them the opportunity for a strong real estate legal system, dollar stability away from their local currency, and still quite affordable. But for those holding land, is now truly the right time to sell, or if you should wait and hold out for bigger potential gains? Selling land isn’t always a clear cut decision, it’s a personal circumstance decision. But market timing, nearby development, and your personal financial goals all play a role. Here are five powerful signs to help you decide whether to sell your land now, or hold onto it for the future. 1. Nearby Development Is Getting Closer If you’re seeing roads being widened, power lines going up, or housing developments creeping toward your area, this could be a prime time to hold. When development reaches your parcel, or gets close the land values often spike way beyond what you’d expect. Have you ever seen city lots selling for $100k plus, sometimes in the millions. Well, someone held strong on that land during its low value days, they watched others sell their land and the area developed. Leaving them with a rare asset within the area now, if anyone wants to buy land and build their options are few and far between. Leaving the land owner with a prime valued parcel. Sometimes it takes years, and maybe even something they had to pass down till it happened. But in the right situation it could create major value for your family. However, if development is simply not happening and you’ve held it a long time, selling now might make more sense if you need the cash. Especially if you can reinvest in a more promising location. As of 2025, if you have just held for a good 3-4 years, there’s a good chance you’re at least 300% up on your value. That’s worlds better than a 401k does, so cashing out isn’t a terrible idea. What to look for: Zoning changes or county meetings about growth New utility access (water, sewer, electric) Nearby homebuilders starting subdivisions 2. Land Values Have Spiked Land is often considered a hedge against inflation. Over the past few years, land values in many areas have risen sharply as people look for alternative investments beyond stocks or traditional real estate. If your land has doubled or tripled in value and you’re not planning to build or use it, now might be the most profitable time to sell. Prices can flatten or decline when interest rates lower or the economy cools. Land is considered a secondary investment, not a primary living space. In times of a downturn, people tend to sell their secondary assets. And the market gets flooded with sales, dropping the values back down. So, if you’re looking for peak value maybe this is the top and you can re-invest during a downturn. But you never know the market, maybe prices continue to rise. It’s always a guess of course. Tip: Use recent sales or get a no pressure quote from a reputable land buyer or agent to gauge value. If you don’t understand how what impacts land values there is a great guide from Investopedia here Land Values 3. You’re Paying Taxes But Not Using the Land One of the simplest signs, your land is costing you a lot of money every year, and not returning anything. Annual property taxes, HOA dues, or weed abatement fees add up, especially on remote or non-buildable land. If you’re holding land where the full annual cost is cheap, $50 a year or something, then it’s nothing to just hold the land long term. But some people, especially within HOA’s could be holding land for annual costs in the thousands. The longer you pay this, you are simply deducting from the profit in the future. You may even go negative on it. If you’ve had it for years with no use, no access, or no realistic future plans, it might be time to cash out and let go of the maintenance headache. Holding a high HOA due property is only good if you plan to build, they rarely go up in value as most don’t want them long term, just builders. 4. Zoning and Access Limit Future Use Some land seems promising, until you dig into the zoning or access. If your land is zoned agricultural, flood-prone, or restricted from building, that could seriously cap future value. Some areas are not buildable and if it doesn’t look like anything will change, it just won’t go up in value. Yes, you could hold till it does become accessible, but sometimes it doesn’t. Issues like lack of firetruck access or land erosion will often have a no build rule, the land might not have the qualities to hold a building. That doesn’t look good for the future, although it’s usually sellable as someone is always willing to take the risk of holding it. Likewise, landlocked parcels with no legal access may look great on a map but be difficult to use or sell. In these cases, waiting doesn’t always make the land more valuable. You may even have to take a loss on these but at least you won’t have to pay annual taxes anymore. If you’ve confirmed through the county that development will be tough or impossible, selling might be the smartest move. 5. Your Financial Priorities Have Changed Life circumstances evolve and so do investment goals. Whether you: Have an emergency Need funds for retirement Want to start a business Pay down debt …selling a piece of idle land can be a strategic way to free up capital without touching your primary assets.